


Abbey Wemimo: Building the Financial Infrastructure That Turns Rent Into Credit
The standard immigrant-founder narrative would frame Abbey Wemimo's path to Esusu as a story of hardship overcome: a childhood in Lagos, a difficult adjustment to Minnesota, a company built from perso
Executive Summary
Every month, tens of millions of renters make an on-time payment that never touches their credit file. The transaction happens, the money moves, and the single most reliable evidence of their financial discipline — paying the largest recurring bill most households carry, on time, month after month — simply evaporates from the record the credit system uses to decide who gets a loan, a mortgage, or a lower interest rate. Abbey Wemimo co-founded Esusu on the observation that this was not a data-scarcity problem. The data existed, generated automatically by property management systems every month. It was a data-capture problem: nobody in the existing credit infrastructure had a reason to collect it. Esusu's rent-reporting platform closes that specific gap, and Wemimo's own experience of being credit invisible — unable to secure a loan despite years of on-time obligations — is the reason he saw a discarded financial signal where the rest of the credit industry saw nothing worth building.
Introduction
The standard immigrant-founder narrative would frame Abbey Wemimo's path to Esusu as a story of hardship overcome: a childhood in Lagos, a difficult adjustment to Minnesota, a company built from personal struggle. That narrative is true, and it is also the least useful way to understand what Esusu actually does. The more precise question is mechanical: what specific piece of financial reality was already being generated, every month, by tens of millions of households, that the credit system had simply never been built to capture — and why did an outsider to that system have to be the one to notice it?
Who Is Abbey Wemimo?
Wemimo grew up in Lagos, Nigeria, and lost his father at age two; he and his mother later moved to Minnesota, where he was 17. The formative event was not the move itself but what happened afterward: his mother, trying to help pay for his college education, was turned away from multiple banks because she had no credit score, despite years of steady, on-time financial obligations. With no access to conventional credit, she pawned his father's ring and borrowed money at an interest rate exceeding 400% from a payday lender to cover the gap — a decision made not from financial irresponsibility but from having no other legible path into the system that determines who is allowed to borrow affordably. Before Esusu, Wemimo had already founded two earlier ventures: a clean-water social enterprise that reached more than 250,000 people across several countries, and a data analytics company gathering machine-readable information on NGOs operating in Africa, later acquired in 2014. Both point to a consistent pattern in his approach well before Esusu existed — treating overlooked or poorly structured information as the actual constraint standing between a population and an outcome it deserved, whether that information concerned water access, NGO accountability, or, eventually, his own family's credit history. That experience, and the recognition that roughly one in ten American adults carries no credit history at all — a population regulators call credit invisible — became the founding premise behind Esusu, which Wemimo co-founded with Samir Goel in 2018.
What Did Wemimo Actually Build?
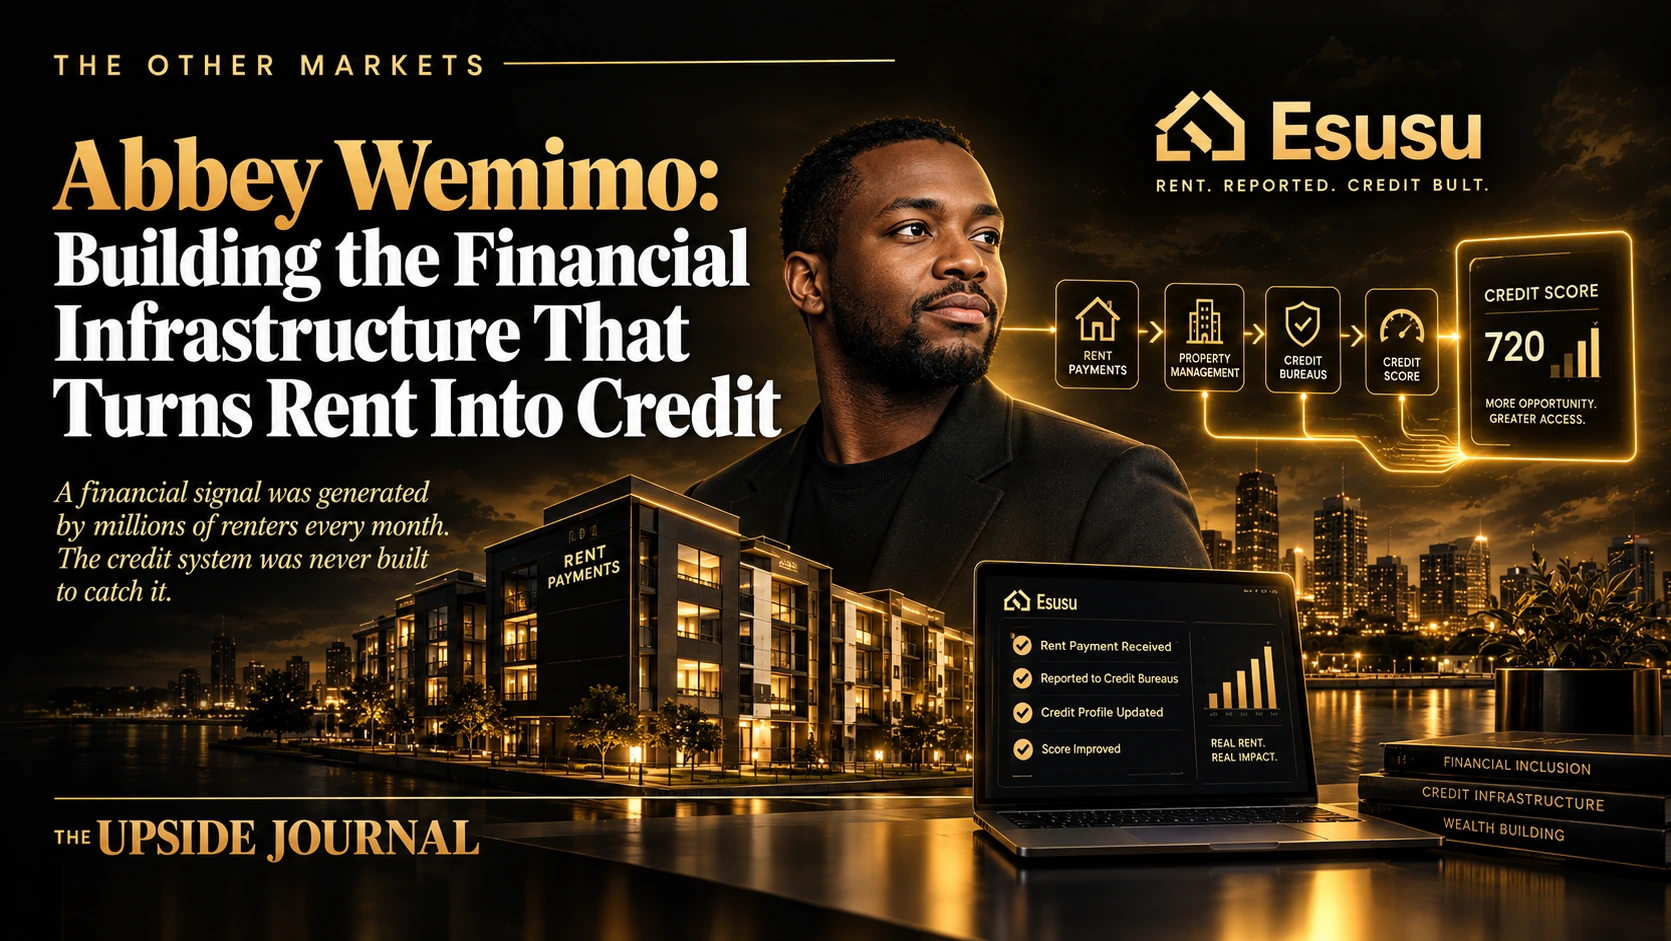
Esusu is a rent-reporting platform: it captures on-time rental payment data from property owners and reports it to the major credit bureaus, converting a transaction that traditionally left no trace in the credit system into a data point that builds a renter's credit history. The mechanism is deliberately narrow in scope — Esusu does not originate credit, extend loans, or replace a credit bureau. It supplies bureaus with a category of payment data they had never systematically received, because no existing institution in the rent-payment chain (landlords, property managers, payment processors) had an incentive or a mandate to report it. The company took its name from a centuries-old West African tradition of rotating community savings groups — itself a form of informal financial infrastructure built by communities excluded from formal banking systems, and a fitting reference point for a company doing, at institutional scale, a version of what those groups always did at community scale: making a person's reliability visible to the people who need to trust it. The product's deeper mechanics and Esusu's broader thesis on rental data are examined elsewhere in this network; the relevant point here is narrower: Wemimo identified a data-capture gap, not a data-scarcity one, and built the connective infrastructure to close it.
Why Is Rent Financially Meaningful Data?
Rent is, for most households without a mortgage, the single largest and most consistent recurring financial obligation they carry — larger, in most cases, than any other bill reported to credit bureaus. A household that pays that obligation on time for years is demonstrating exactly the behavior credit scoring models are designed to measure: reliable, disciplined repayment. That the traditional credit system never captured this signal was not because the behavior was rare or the data didn't exist; it was because the infrastructure connecting property managers to credit bureaus had simply never been built. Esusu's core insight was that this was a solvable infrastructure problem, not an intractable data problem — the payment records already lived inside property management software; they had never been routed anywhere that mattered to a renter's financial identity.
What Infrastructure Gap Did This Address?
The gap Wemimo identified sits precisely between two systems that had no reason to talk to each other: property management, which records whether rent was paid on time, and credit reporting, which decides whether a person is deemed creditworthy. Mortgage payments have long fed into credit scores because mortgage lenders are themselves part of the traditional credit and banking system, with every incentive to report. Landlords and property managers were never part of that system, and building the connective plumbing between the two required a company willing to treat that missing link as its entire product — not a feature bolted onto an existing lending business, but the business itself.
How Large Is the Gap Esusu Is Actually Closing?
The credit-invisible population is not a marginal edge case. The Consumer Financial Protection Bureau's own research puts the number of credit-invisible American adults at roughly 26 million, with an additional 19 million holding credit records too thin or outdated for a lender to reliably score — a combined population in the tens of millions, disproportionately concentrated among renters, younger adults, and immigrants, the exact population least likely to already hold a mortgage, the traditional route into a credit file. Esusu's own reach gives a sense of how much of that gap a rent-reporting infrastructure can realistically address: the company has worked with property owners covering several million rental units nationwide, representing tens of billions of dollars in reported rent payments — not because that scale was the goal in itself, but because it is the natural size of the problem once the connective infrastructure exists to capture it. A gap measured in tens of millions of people does not close through individual willpower or better financial literacy; it closes only when someone builds the plumbing connecting a payment that was always happening to a system that had never been built to see it.
Why Didn't an Existing Institution Build This First?
The more uncomfortable question is why this infrastructure did not already exist, given that the underlying data — on-time rent payments — had been sitting inside property management software for decades before Esusu's founding in 2018. The answer is structural rather than technical: no participant already inside the existing credit and housing system had a strong enough incentive to build the connective layer. Credit bureaus profit from the reporting relationships they already have with mortgage lenders and credit card issuers; adding a new category of reporting partner required outreach, integration work, and standard-setting that no bureau was independently motivated to pursue at scale. Property managers had no reporting mandate and, in many cases, no awareness that the data they already collected had value beyond their own operations. Neither side of that relationship was positioned, or incentivized, to build the bridge between them — which is precisely the condition under which infrastructure gaps tend to persist indefinitely until an outsider, with no stake in either existing system's status quo, decides to build the missing layer as a standalone business.
Why This Matters for Founders and for Policy
For founders evaluating where genuine infrastructure gaps still exist, Wemimo's path argues for a specific kind of pattern recognition: the most durable gaps are often not places where technology is missing, but places where two existing systems generate and consume closely related information without ever having been connected — property management and credit reporting, in this case. Those gaps tend to persist longest not because they are hard to see, but because no incumbent on either side benefits enough from closing them to bother. For policymakers and institutional observers, the credit-invisible population Esusu addresses is a reminder that access to capital is often gated well before the point of a loan application — at the more basic level of whether a person's financial behavior is visible to the system deciding their creditworthiness at all. Rent reporting does not solve financial exclusion on its own, but it addresses one specific, previously unaddressed layer of it: making a genuinely disciplined financial behavior legible to a system that had simply never been built to see it.
Why This Matters Beyond Esusu Itself
The pattern Wemimo's path illustrates recurs across this network. Ridwan Olalere built LemFi on the same underlying premise applied to a different underserved population: diaspora communities poorly served by incumbent remittance rails, addressed not with a cheaper transfer app but with the missing payments infrastructure itself. Joe Kinvi's Borderless applies the same logic to diaspora investment access. Wemimo's version of the pattern has no diaspora customer base at all — Esusu serves any credit-invisible renter regardless of background — and that is precisely what makes the underlying pattern worth naming: a founder who has personally experienced a structural financial gap builds the infrastructure that an incumbent system, with no incentive to notice the gap, never built. LemFi's own consolidation of a fragmented financial stack, examined on its own terms elsewhere in this network, previews the shape Esusu's own product-layer story will take in a forthcoming companion piece.
This also connects to a broader argument this network has made about capital access: the diaspora capital stack that determines who gets funded assumes, at its foundation, that a person's financial reliability is visible to the institutions making that decision. Credit invisibility is a precondition failure underneath that entire stack — a person with no credit history is effectively invisible to the same institutional capital this network otherwise tracks in terms of remittances, angel networks, and venture funding. Esusu's contribution sits one layer beneath that story: it is infrastructure for being seen by the financial system at all, before any question of what that system then does with the person it now recognizes.
Where This Doesn't Fit
This is a founder-and-mechanism piece, not a product walkthrough. It does not detail Esusu's technical integration with property management systems or credit bureaus, evaluate the company's unit economics or valuation history, or lay out Esusu's broader thesis on what rental data specifically reveals about creditworthiness — each of those belongs to a separate node in this cluster. Nor is this a comprehensive biography; Wemimo's earlier ventures and career history are relevant here only insofar as they establish the operating thesis behind Esusu, not as a subject in their own right.
Key Takeaways
- Roughly one in ten American adults is "credit invisible" — carrying no credit history at all, regardless of how reliably they pay other obligations.
- Rent is most renters' largest recurring financial obligation, yet it historically generated no data point in the credit system that decides their access to loans, mortgages, or lower interest rates.
- Esusu's insight was that this was a data-capture problem, not a data-scarcity one: the payment records already existed inside property management systems, with no infrastructure routing them to credit bureaus.
- Wemimo's own experience — his mother turned away from banks and forced into a 400%-interest loan despite years of reliable payments — supplied the specific clarity to see a discarded financial signal where the existing credit industry saw nothing worth building.
- Esusu belongs to a wider pattern of founders building the infrastructure an incumbent financial system had no incentive to build itself, alongside LemFi and Borderless elsewhere in this network.
Conclusion
The instinct to read Abbey Wemimo's story primarily as personal triumph is not wrong, but it understates what Esusu actually is. The company's significance rests less on being another fintech success and more on the specific recognition that a major financial signal — on-time rent, paid by tens of millions of households every month — was being generated continuously and simply discarded by a credit system that had never been built to capture it. That the founder who noticed this had lived the consequences of the gap himself is what made the observation actionable rather than academic; it does not change what the infrastructure itself does, or why it was missing in the first place. The next question this network will take up is what Esusu's own product does with that captured signal once it reaches a credit bureau — a question this piece has deliberately left for the node built to answer it.