


How LPs Evaluate African Venture Capital Funds: What Institutional Investors Look For
Ask a fund manager what limited partners look for in an African venture capital fund, and the answer usually arrives as a list — team, thesis, track record, terms. That's directionally true and analyt
Executive Summary
African venture capital funds are frequently described as attracting limited partners. That description explains nothing about why one fund closes and a structurally similar one does not. LP Fund Selection is a capital-allocation decision, not a scorecard of fund characteristics: it runs mandate through fund strategy, evidence, risk, portfolio construction, and governance before an allocation is ever approved. Africa complicates that sequence in one consistent direction — thinner realized track records, currency-mismatched fund structures, and an anchor-investor base now mid-restructure. This piece maps what institutional investors actually test for when backing an African VC fund, how they assess emerging managers without a decade of distributions behind them, and what ultimately separates a fund that gets funded from one that only gets meetings.
The Checklist Answer Is the Wrong Answer
Ask a fund manager what limited partners look for in an African venture capital fund, and the answer usually arrives as a list — team, thesis, track record, terms. That's directionally true and analytically empty: it describes what shows up in a pitch deck, not what an investment committee is actually testing for before committing capital it cannot easily recall.
Limited Partners (LPs) are not buying exposure to African startups. They are underwriting a General Partner's (GP's) ability to convert a stated strategy into a risk-adjusted return, inside a market whose broad structure this network has already mapped in detail. This article treats fund selection the way an institutional allocator's investment committee would: as a sequence of gates, each one capable of ending the process, not as a single yes-or-no verdict on a pitch deck.
The Decision Architecture: How an Allocation Actually Gets Approved
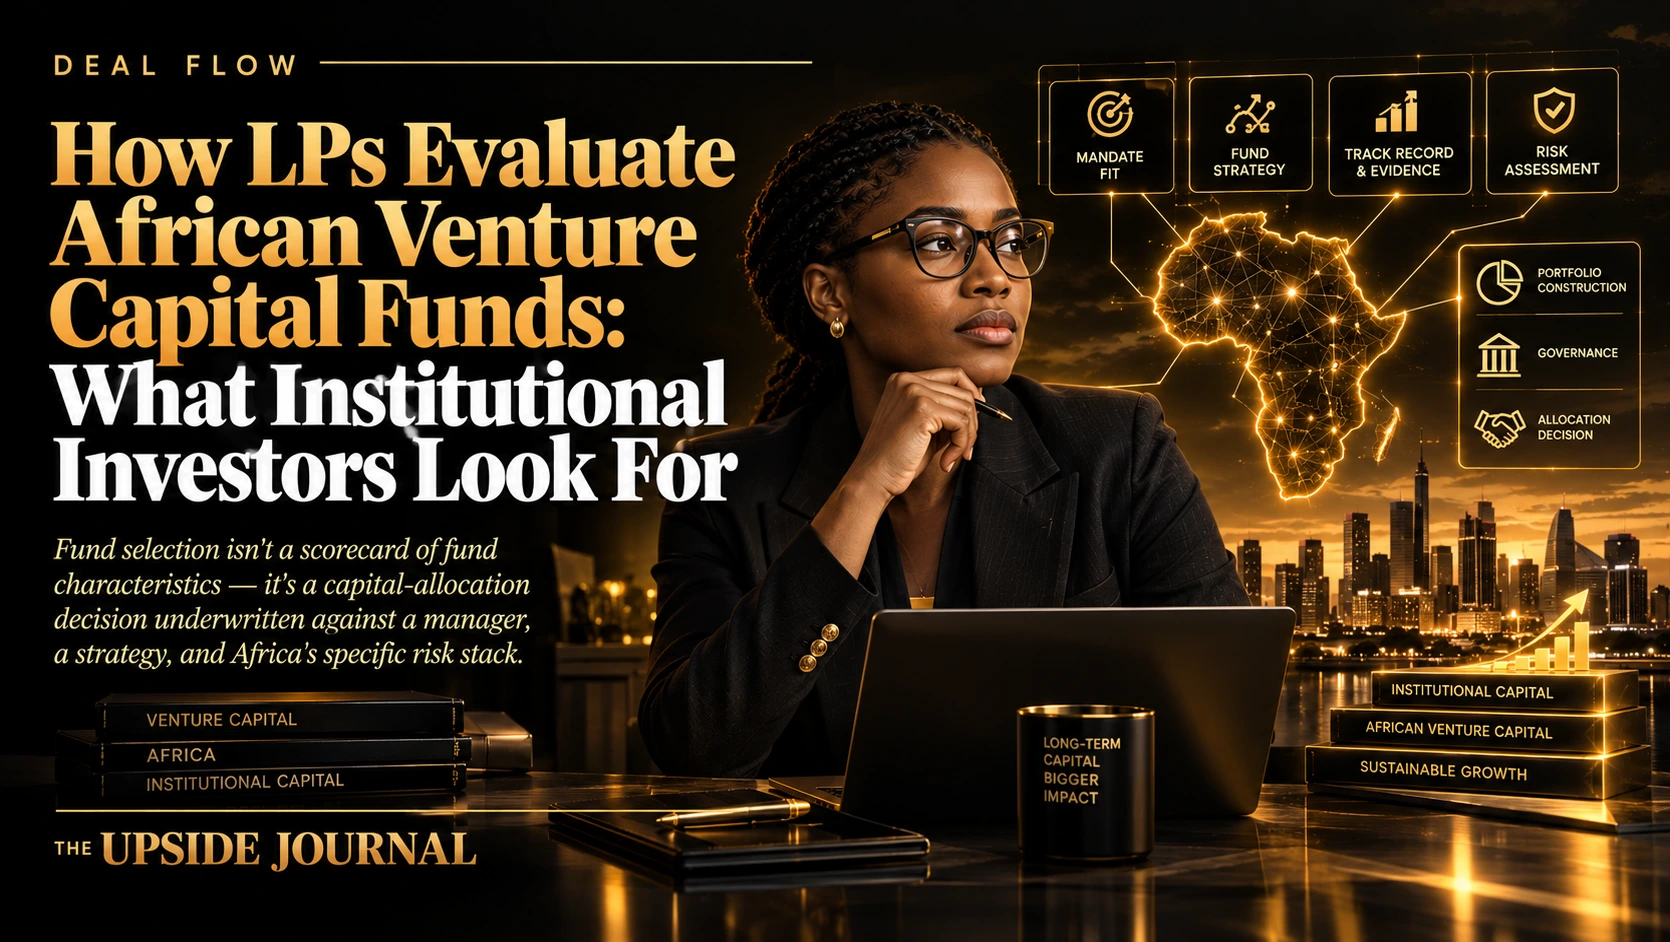
An LP's evaluation of an African VC fund moves through seven gates, in order: mandate fit, fund strategy, evidence, risk, portfolio construction, governance, and only then, the allocation decision itself. Skip a gate and the fund doesn't get fast-tracked — it gets rejected later, at a more expensive stage of the process.
Mandate fit comes first because it is unappealable: a fund can be excellent and still fail this gate if it doesn't match the LP's return profile, geography, check-size, or (for a development finance institution) impact mandate. Fund strategy asks whether the manager's stated thesis — sector, stage, geography, check size — is specific enough to be tested against evidence, rather than broad enough to justify almost any deal after the fact. Evidence and risk are where track record, team, and market conditions get stress-tested. Portfolio construction asks whether the fund's stated reserve strategy, follow-on discipline, and ownership targets are mathematically consistent with its fund size. Governance tests whether the operational infrastructure around the fund can be trusted with capital regardless of how good the thesis is. A fund that survives all seven gates gets an allocation. A fund that is merely interesting at gate three does not.
What Institutional Investors Actually Evaluate
Fund Economics and Alignment
Management fee, carried interest, and the GP's own capital commitment to the fund are read together, not separately: a below-market GP commitment paired with an above-market fee is a signal about whose risk is actually being carried. The question isn't whether terms are generous — it's whether they align the manager's incentives with the LP's, over a ten-year fund life.
Investment Thesis Specificity
A thesis that can explain any deal in the portfolio is not a thesis; it's a description written after the fact. LPs test whether a stated sector or stage focus actually constrained the manager's last twenty decisions, not just the two decisions in the pitch deck.
Portfolio Construction Discipline
This is where venture capital's underwriting logic diverges from private equity's: VC portfolio construction assumes most positions fail and a small number carry the fund, so LPs test whether reserve ratios and follow-on capacity are sized for that outcome distribution, not for a smoother, PE-style loss curve.
A fund that scores well on thesis and team but fails portfolio-construction math isn't a marginal fund — it's a fund that will run out of reserves exactly when its best companies need them most.
How Africa Changes the Underwriting Problem
Africa doesn't change what LPs evaluate. It changes how much evidence exists to evaluate it with, and who is asking the questions in the first place.
Development finance institutions historically supplied roughly 45% of commitments into Africa-focused venture funds between 2022 and 2024, anchoring first closes and absorbing the illiquidity risk that commercial capital wouldn't touch. In 2025, that share fell to 27%. Corporate LPs moved into the gap, rising from roughly 7% of commitments to 41% over the same window — a shift in incentive structure, not just in balance sheet. Africa-focused managers closed just $107 million across six vehicles in 2025, an 87% year-on-year drop by value. The retreat is real, but it is not uniform: development finance institutions like Africa Finance Corporation have moved from writing infrastructure cheques toward backing VC managers directly, a $40 million commitment to two firms in 2026 being the clearest recent signal that DFI capital is repositioning rather than disappearing. That repositioning matters for this piece's scope specifically: why corporate LPs are becoming Africa's fastest-growing LP category is its own node; here, the relevant fact is only that the LP base an emerging manager is pitching in 2026 has a materially different risk appetite than the one a manager pitched in 2022.
A second, structural distortion sits underneath the LP-composition shift: most African VC funds are raised and denominated in US dollars, while the revenue of their portfolio companies is earned in local currency. That mismatch doesn't show up in a pitch deck's headline multiple, but it shows up in every distribution an LP eventually receives, converted back through a currency that has moved against the fund since the initial cheque was written. An LP evaluating an African fund is underwriting currency risk whether or not the term sheet says so — a structural feature the fund's stated strategy was never going to compensate for on its own.
Assessing Track Record When There Isn't Much of One
Standard venture capital track-record metrics are IRR (internal rate of return, which measures the speed of returns), TVPI (total value to paid-in, which measures value created including unrealized marks), and DPI (distributions to paid-in, which measures cash actually returned to LPs). For an established fund, these three numbers, benchmarked against same-vintage peers, do most of the evaluative work. For a first- or second-time African manager, DPI rarely exists yet — most funds don't return meaningful cash before years six to twelve of a ten-year life — and TVPI on a young African portfolio is a paper number an LP has no independent way to verify.
Institutional LPs compensate with proxy signals rather than abandoning rigor. They ask for named LP references from the manager's prior fund or angel track record and expect those references to actually take the call. They look for fast follow-on validation — whether Tier-1 co-investors backed the manager's early checks on similar terms, rather than the manager backing deals no one else would take. They check whether the fund is sized to the strategy: an oversized fund chasing a thin deal pipeline is a portfolio-construction failure before it is a returns problem. And they benchmark the manager against funds of comparable size, geography, and vintage — not against a generic top-quartile figure drawn from funds ten to fifty times larger. None of this is unique to Africa; what's specific to the market is that deal-count activity and capital deployed are not the same evidence, and a manager's visibility in deal-flow rankings tells an LP almost nothing about the fund-construction discipline underneath it.
Governance and Operational Due Diligence
Institutional Limited Partners Association's Due Diligence Questionnaire — the standardized framework most institutional LPs use as a baseline — splits evaluation into three distinct workstreams: investment due diligence (strategy, track record, deal sourcing), organizational due diligence (team composition, key-person risk, succession planning, carry allocation among the team), and operational due diligence (governance, compliance, fund administration, valuation policy, cybersecurity). The first workstream is what most fund pitches are built to answer. The other two are frequently where an allocation is lost.
Operational due diligence tests whether the fund can be trusted with capital independent of whether its thesis is right. Valuation policy is a specific pressure point: LPs expect quarterly valuation cadence, adherence to recognized guidelines, and, increasingly, independent third-party review of illiquid positions at least annually. Key-person risk is another: a fund built around one general partner's network and judgment, with no documented succession plan, is a governance gap regardless of that partner's individual track record. A fund with an excellent thesis and a weak operational backbone doesn't fail on merit — it fails on trust, which is a harder gate to pass a second time.
Where LP Fund Selection Fits
This piece is deliberately narrow. It does not explain how a venture fund's deal flow, structure, and returns mechanics actually work — that operating-system layer is a separate node this network has already covered, and repeating it here would only dilute what's specific to the LP's side of the table. It does not map which individual firms are currently most active by deal count; that firm-level view exists elsewhere and answers a different question than the one an allocator's investment committee asks. And it deliberately stops short of the mirror question — how an emerging African manager actually gets backed, tactically, from the fundraising side of the same negotiation — which belongs to its own forthcoming piece in this network, not to a chapter buried inside this one.
What belongs here, and only here, is the LP's internal decision architecture: the sequence an allocation has to survive, gate by gate, before capital moves.
Why This Matters for Institutional LPs and Emerging GPs
For institutional LPs — and particularly for the corporate investors now filling the space development finance institutions are vacating — the practical implication is that Africa-specific underwriting can't be outsourced to a generic global VC diligence template. Currency mismatch, proxy-signal track-record assessment, and a fast-moving anchor-investor base are conditions a global template wasn't built to price.
For emerging African GPs, the implication runs the other way: fundraising materials built to be interesting will not survive an investment committee built to test for investability. A pitch deck answers "why should you care." A due diligence questionnaire answers "can we trust you with capital for ten years." Those are different documents, testing different things, and conflating them is the single most common reason a promising fund never closes.
Key Takeaways
LP fund selection is a sequential capital-allocation decision — mandate, strategy, evidence, risk, portfolio construction, governance — not a static checklist of fund characteristics.
Africa doesn't change what LPs evaluate; it changes how much evidence exists to evaluate it with, and development finance institutions falling from 45% to 27% of commitments while corporate LPs rose to 41% has reset who is asking the questions.
Track record for African emerging managers is assessed through proxy signals — named references, fast follow-on validation from credible co-investors, and vintage-peer benchmarking — because realized DPI rarely exists this early in a fund's life.
Operational due diligence, not investment due diligence, increasingly decides allocations: governance, valuation independence, and key-person risk carry as much weight as the thesis itself.
A fund becomes institutionally investable the moment its structure, not just its story, survives underwriting — and that is a materially different bar than simply being interesting.
Conclusion
LP fund selection was never a scorecard exercise, and treating it as one is why so many fundraising narratives misfire. It is a capital-allocation decision that runs through mandate, strategy, evidence, risk, portfolio construction, and governance — and Africa doesn't change that sequence, it changes the evidence available at each gate. The LPs backing African venture capital funds today are not simply buying exposure to African startups; they are underwriting a manager, a strategy, a currency structure, and an institution's ability to convert opportunity into a risk-adjusted return over a decade. Funds that understand which gate they're actually being tested at close. Funds that only understand how to be interesting do not.
External References
ILPA: Due Diligence Questionnaire — the standardized institutional framework behind the investment/organizational/operational due-diligence split described in this piece.
Africa Private Equity News: Decoding the Rise of Corporate LPs — primary evidence for the 2025 shift in DFI and corporate LP commitment shares
TechCabal: Why AFC Backed Future Africa and LightRock With $40 Million — a named, current example of a DFI repositioning from infrastructure finance into direct VC-fund LP commitments.
Value Add VC: Emerging Manager Track Record — LP Criteria — backs the track-record-substitution argument with vintage-year performance data.